

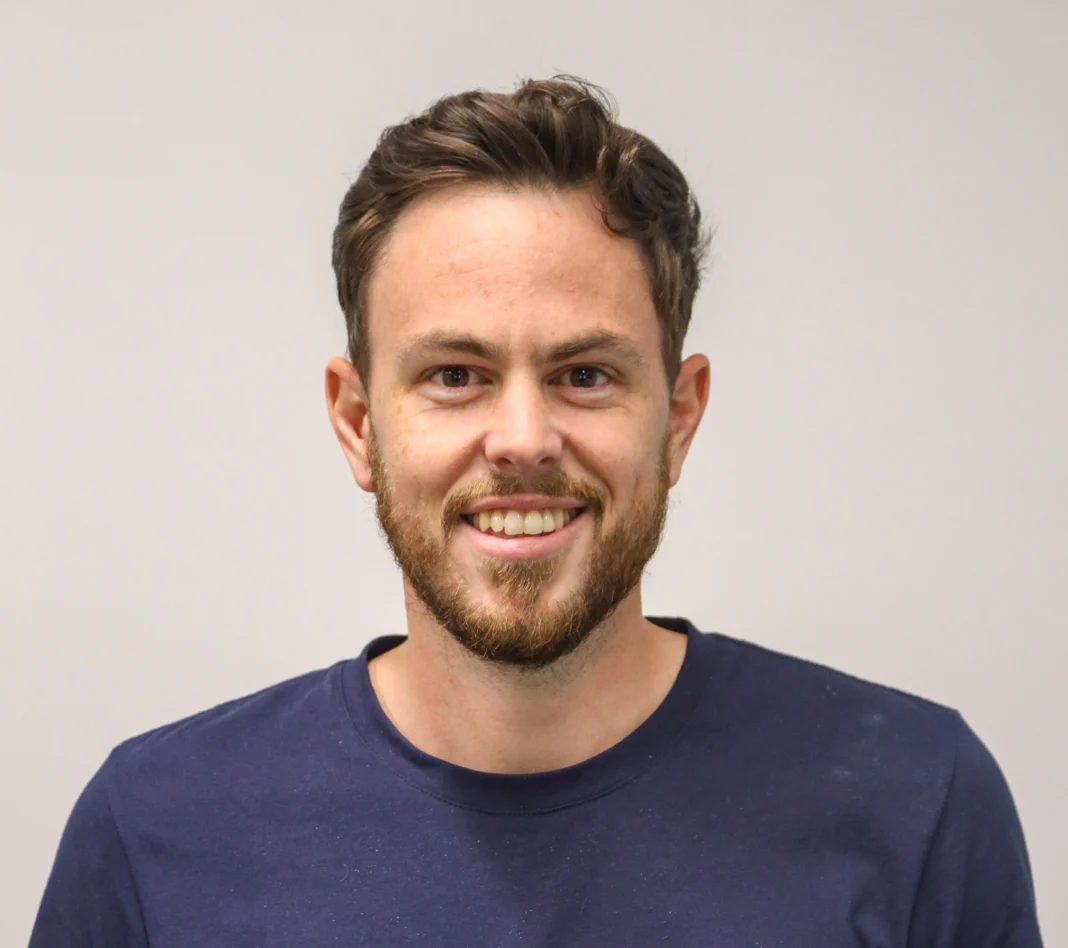
As South Africa debates whether to legislate against late payment, Lulapay’s Vice President, Jordan Gosling, talks about how the need for suppliers to extend their terms to their own customers has turned them into involuntary lenders.
As South Africa considers stronger protections against late payment Lulapay’s Vice President Jordan Gosling argues that payment terms are effectively turning suppliers into involuntary lenders. He believes the starting point is recognising what payment terms represent and creating solutions that resolve the direct challenge, for both buyer and supplier.
“When a supplier delivers goods or services today but agrees to receive payment in 30,60 or 90 days, it is extending credit,” he explains, “The supplier is carrying the cost of labour, stock, tax and operations while the customer retains the cash. In practical terms, suppliers have become involuntary lenders.”
Trade credit is often described as a routine feature of doing business, however this language hides the risks taking place between supplier and buyer. A bank can choose whether to lend, assesses the borrower, prices the risk and sets the conditions for repayment while a supplier rarely has this level of freedom. Many accept lengthy terms because a large customer insists on them and rejecting those terms could cost the contract, or challenging a late payment invariably jeopardises future work. The supplier is financing the customer without necessarily earning interest or receiving security.
The challenge is finding an innovative way to bridge the gap between payment terms and supplier need, one that isn’t necessarily going to be fixed by more legislation. Currently, the SME’s only alternative is to pay upfront to secure a deal, and if they are light on cash, the deal doesn’t go through. Recently re-launched with features that support both the supplier and the customer, Lulapay flows cash on both sides of the deal to ensure it goes through, benefitting both the buyer and the supplier. It bypasses the delays with a secure solution that puts the business back on the proverbial drawing board.
A rule implemented by any form of legislation needs to be supported by visibility and consequences and there needs to be a practical and enforceable route that suppliers can follow to enforce their rights without destroying commercial relationships. It’s at this intersection of need and relationship that solutions like Lulapay play an important role – instead of SME’s running the risk of bad debt while waiting on a customer’s ability to pay, they can avoid lost sales and late payments with a payment solution that enables wholesalers, suppliers and distributors to grow sales and eliminate credit risk by settling invoices upfront.
Suppliers are often left carrying the cost and they face funding gaps that they need to overcome to ensure their cash flow can keep up with demand. “When a company comes to us because their customers are slow to pay, it is rarely a distress signal,” says Gosling. “It usually means the orders are there and the relationships are good, but the cash needed to keep trading while the invoices clear is missing. Access to funding at this point is a sign of health.”
The regulatory debate, he argues, is aimed at the right problem but reaches for a blunt instrument. Statutory payment terms and mandatory interest may compel faster payment in some cases, but they do little for the supplier who needs money now and can’t wait for a dispute to resolve. “Regulation can change what people are obliged to do,” says Gosling. “It cannot change the fact that a business needs cash on the day the bill lands, not when a tribunal decides it was owed.”
It is a distinction Lulapay sees clearly because of how its own products are structured. Lulapay assesses a customer’s cash flow and ability to generate revenue and treats that as an asset, funding against it to give businesses access to revenue they have yet to earn. The funding is built around future revenue rather than issued as a conventional loan. The company is a founding member of the South African SME Finance Association (SASFA), which represents the self-regulating, non-bank alternative lending sector and aligns with a code of conduct that requires transparency, fair treatment, responsible lending and strict prohibition on loan stacking and predatory behaviour. The platform’s structure has been reimagined and redefined to ensure that both supplier and buyer receive support and funding at the right time. Lulapay pays the supplier upfront, the buyer repays Lulapay over an agreed term so the supplier is paid immediately with no credit risk and the buyer gains room to manage cash flow on their stock purchases. It changes the narrative from complex and rigid to a flexible and secure financial management solution that benefits all parties involved.
“Introducing rigid statutory terms could load the market with compliance cost without touching the macroeconomic and administrative causes of slow payment,” says Gosling. “Cash flow in a real business fluctuates and if reform removes that flexibility, it will make the problem worse. That said, reform is important – well-designed oversight would support SASFA’s goal of moving the market away from distress lending towards long-term growth-oriented funding. This would lower the structural default risk and let accredited lenders offer fairer, more transparent and lower-cost working capital.”
Lulapay closes the gap between the moment a bill lands and the payment of an invoice, providing companies with a solution that settles the invoice upfront while giving the customer time to pay. Because Lulapay’s agreement is with the buyer, the supplier carries no recovery risk if the buyer defaults and they stop being an involuntary lender. To date, Lulapay has disbursed almost R1 billion in funding across 600 SMEs.
“Our customers aren’t looking for a safety net, they’re looking for a way to say yes to more customers without financing them,” concludes Gosling.