

The measures announced by Finance Minister Enoch Godongwana in this week’s Medium-Term Budget Policy Statement (MTBPS), including temporary fuel levy relief aimed at easing pressure on South African households, will not on their own address the structural challenges affecting access to homeownership.
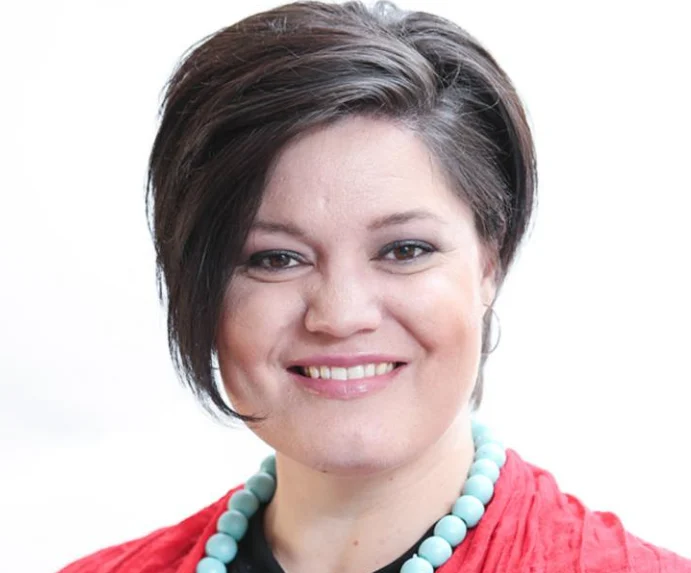
“Improving access to homeownership requires a broad approach that considers interest rates, employment and income levels, credit access and the availability of suitable housing stock,” says Esteani Marx, Business Development Executive at Lightstone Property.
Lightstone Property’s bond-financing research highlights the barriers to homeownership, particularly among younger buyers and those entering the affordable housing market.
“Interest rates are an important factor in determining what buyers can afford, but the bigger question is whether households have the financial capacity and access to funding needed to enter the property market in the first place,” says Marx.
Lightstone’s analysis from 2011 to 2025 shows that mortgage activity generally rises as interest rates fall, although structural constraints persist. Bonded property transfers increased from around 110 000 in 2024 to 118 000 in 2025, but longer-term volumes have remained relatively flat.
Younger buyers face particular challenges: those under 35 accounted for 31% of the value of bonds issued in 2025, compared with around 40% at their 2005 peak. “This suggests that affordability pressures are not simply delaying individual purchasing decisions. They are also influencing when South Africans can enter the property market and begin building wealth through home ownership,” says Marx.
First-time buyer transactions in the affordable segment fell from around 32 000 in 2021 to 22 000 in 2025, with only 38% bond-financed in 2025. In the middle-to-upper market, first-time buyer transactions declined from 77 000 to 57 000 over the same period.
The September 2026 repo rate increase to 7.25% added to borrowing costs. Proposed fuel levy relief may ease household expenses, but it does not directly resolve barriers to housing finance.
Marx says improving access to homeownership in South Africa requires addressing broader structural challenges, including household affordability, the availability of appropriately priced housing, access to finance and the upfront costs of purchasing property.
“Greater alignment between household income levels, housing supply, lending practices and infrastructure development is essential to making homeownership more attainable. Ultimately, progress should be measured not only by how many South Africans qualify for home loans, but by how many can realistically afford to purchase and sustainably maintain a home,” she says.
Get the full Lightstone Property insights here: https://corporate.lightstone.co.za/result/Articles/23451.
About Lightstone
Lightstone provides comprehensive data, analytics and systems across the automotive, property and business sectors. Through proprietary datasets, advanced modelling and digital platforms, Lightstone enables more informed decision-making across multiple industries.