

South Africa’s challenger payment providers are putting forward practical proposals of their own for the National Payment System, in addition to responding to regulators’ consultations, and ASAPP’s work on interchange and PayShap now forms part of the decisions on the future of the country’s payment system.
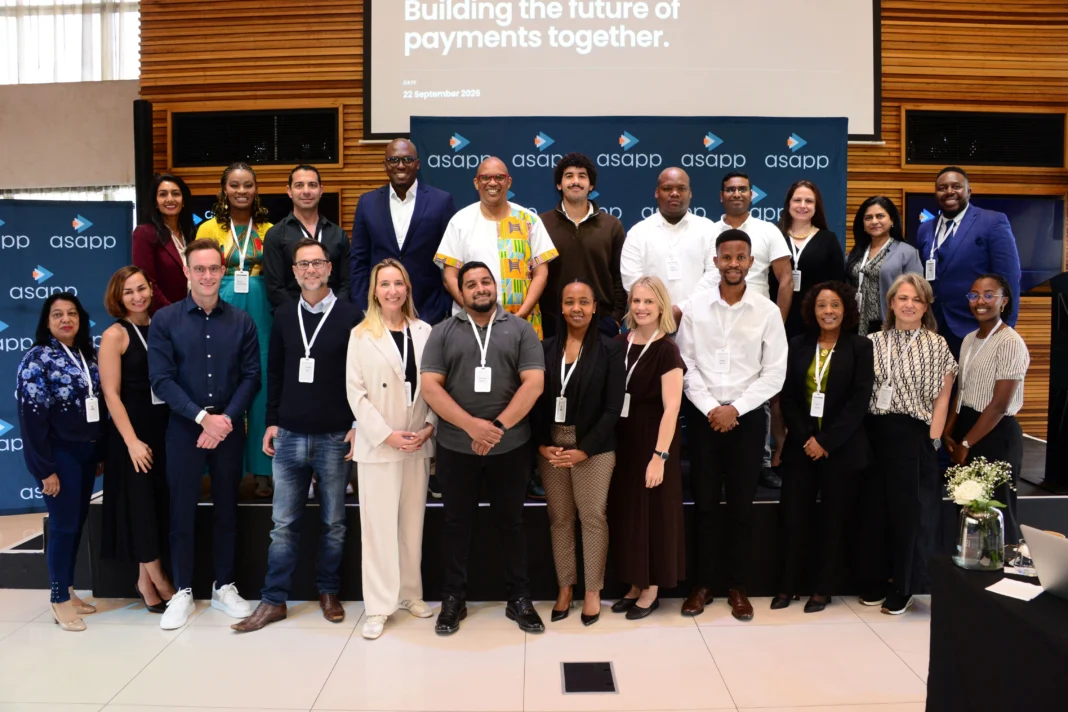
This was reinforced at today’s Association of South African Payment Providers (ASAPP) Strategy Session and media briefing held in Sandton, Johannesburg.
Key achievements to date
A significant milestone for ASAPP is that its input is helping to inform the South African Reserve Bank’s Interchange Determination Project. Interchange fees are paid between financial institutions on card transactions and are one of the main factors in the cost of accepting digital payments.
ASAPP has submitted two Cost of Payments and Interchange papers examining the payment cost stack, international approaches and the extent to which reductions in payment costs ultimately reach merchants and consumers. The SARB has confirmed that ASAPP’s interchange work is being taken into account in the Interchange Determination Project.
ASAPP has also developed and submitted a proposal to the SARB’s National Payment System Department on PayShap merchant acceptance and interoperability. The proposal considers how existing acquiring and merchant-acceptance infrastructure could be used to extend PayShap acceptance and support wider adoption of instant payments.
These proposals reflect a change in how the Association works: ASAPP now puts forward its own positions and practical proposals, supported by evidence, for consideration by regulators, infrastructure providers, and other industry stakeholders.
ASAPP has also grown from eight founding members to a broader and more varied membership, bringing together fintech payment providers, banks, aggregators, service providers, and payment platforms.
“Every member of ASAPP chose to build in a market where the incumbents already held the customers, the infrastructure, and the rules. We are challengers. We challenge commercially, by winning customers with better products, and we challenge in our advocacy, by showing the regulator with evidence where a rule serves the past and what we would support in its place,” says ASAPP President, Lincoln Mali.
A collective industry voice
The Association of South African Payment Providers was established in early 2024 to provide fintech payment providers and other payment participants with a coordinated industry platform and to promote fair and competitive participation in the National Payment System.
According to FinMark Trust’s FinScope national research surveys in 2024 and 2025, nearly 9.5 million South Africans earn income through the informal economy. While 71% of SMEs receive some digital payments, 89% say their customers still pay in cash and only 28% have a point-of-sale device. Furthermore, while 89% of South African adults have a bank account, approximately five million remain unbanked. Of those with an account, around 13 million use it primarily only to receive and immediately withdraw money.
South Africa’s continued reliance on cash, particularly among underbanked consumers, informal traders and small businesses, many of whom remain excluded from digital payment systems, was central to ASAPP’s formation. From the outset, the Association has focused on three objectives: fair access to payment infrastructure and digitalisation incentives, reducing the wholesale cost of digital payments, and improving customer mobility and transparency.
“ASAPP has evolved from an industry initiative into an established representative body that is increasingly contributing substantive positions and practical proposals to the payments reform agenda. Our focus is not simply on identifying barriers, but on putting forward workable alternatives that can be considered with regulators and industry stakeholders. Our members spent years asking for the rules to be opened up, and we will not ask for rules that rebuild the barriers we argued against. One day a member of this Association will be the incumbent and a business none of us has heard of will be the challenger, and the rules we ask for now should be ones we would accept then,” Mali says.
ASAPP progress
ASAPP’s regulatory and industry participation has broadened considerably over the past year.
ASAPP has participated in the SARB’s Payments Ecosystem Modernisation Programme, faster-payments initiatives and NPS Vision 2030+, and has engaged directly with the National Payment System Department on regulatory reform, industry governance, fraud initiatives, domestic processing, PayInc developments and future scheme governance.
ASAPP representatives have also participated in five of the six National Treasury Technical Working Groups established to support development of the National Financial Inclusion Strategy.
During the year, the SARB and NPSD formalised their engagement with ASAPP as an industry association, providing a standing basis for participation in relevant policy, regulatory and industry consultation processes.
ASAPP has contributed to the proposed National Payment System Bill, which aims to modernise the regulation of South Africa’s National Payment System. Its work includes submissions on PCC118A and cloud computing, as well as industry-governance proposals relating to participation in the structures that will shape the future payment system.
ASAPP has also made submissions and engaged with the SARB on the Banks Act Exemption and Authorisation Framework, including the future authorisation of payment activities and the conditions under which appropriately regulated fintech payment providers and other participants will be able to participate in the payments ecosystem.
“The PayShap proposal is a good example of the approach we want to take. Our members have set out how existing acceptance infrastructure could support wider merchant adoption and pave the way for PayShap to become the payment method of choice for South Africans, and have submitted that proposal to the NPSD,” says Mali, who is also Chief Executive Officer of Lesaka Technologies, one of ASAPP’s founding members.
A critical period for South Africa’s payment system
More of the rules of South Africa’s payment system are coming up for decision in these few years than in the previous twenty. South Africa is progressing significant reforms across payment regulation, infrastructure, faster payments, interoperability, fraud prevention, and digital identity, while longstanding payment-system governance arrangements are also changing.
The decisions being taken now will influence who can participate in the National Payment System, how providers gain access to infrastructure, how payment services interoperate, and what it ultimately costs merchants and consumers to transact digitally. The National Payment System Act is twenty-eight years old, and few in the industry will see its rules rewritten at this scale twice.
On 2 September the last of PASA’s functions transferred to the SARB and PayInc, and continued industry engagement will determine how fintech payment providers and other participants take part in the new governance and infrastructure arrangements.
“Together, these changes can move more of the economy from cash to digital payment. Lower acceptance costs hand margin back to small merchants, a record of digital sales gives a trader a history that a lender can read, and the SARB estimates the gain at up to 0.5% of GDP. Those gains are within reach, and none is guaranteed until the reforms are put into practice,” Mali says.
Priorities for the next phase
ASAPP’s next phase will focus on progressing agreed priorities across four areas: Market Access; Infrastructure & Payment Rails; Cost of Payments; and Identity, Data, Fraud & Cyber.
The intention is to take the positions and proposals developed by members into focused work with regulators, infrastructure providers and other stakeholders, with clearer outputs and accountability for delivery.
For ASAPP, the measure of progress will ultimately be whether reform results in participation, greater interoperability, more competitive payment economics, and wider digital-payment adoption, particularly for merchants and consumers who remain heavily dependent on cash.
ASAPP has also recently joined the SME Finance Forum, providing an additional platform for engagement on issues affecting SMEs, financial inclusion and the role of payment providers in supporting access to digital financial services.